 ×

Co-Location Wind + BESS in Germany
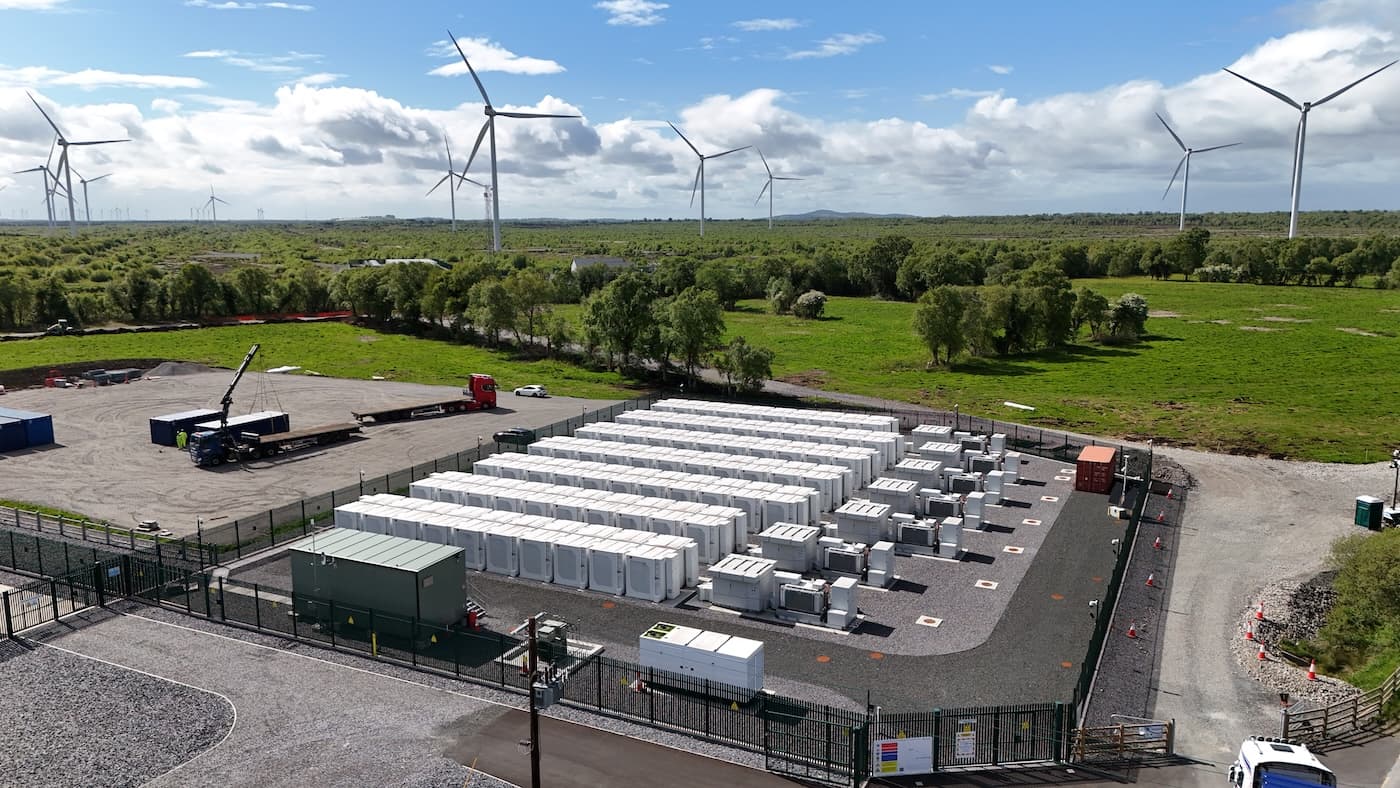
A techno-economic study of a 25 MW co-located wind + battery energy storage system (BESS) project in Germany, evaluated across five forward price scenarios and three configurations: wind alone, wind combined with a Green BESS, and wind combined with a Grey BESS.
Jointly produced by phelas and Fluence. Combining Fluence’s BESS dispatch and grid-services expertise with phelas’s techno-economic project modelling to evaluate co-located wind + storage at the project level.
01 · Executive Summary
Storage makes the wind project bankable. Charging from the grid widens the margin.
Across five German price scenarios for 2027–2056, a standalone 25 MW wind project earns an IRR of 7.5% to 12.5%. Since the majority of the scenarios end up close to the 8% weighted average cost of capital, the margin is too thin to finance the project on its own.
Both wind + BESS configurations, Green and Grey, raise the IRR clearly above the 8% hurdle rate in almost all scenarios. A Green BESS, which charges only from the wind park, raises the lowest IRR to 8.4%, while the other scenarios range up to 14.1%. A Grey BESS, which may also charge from the grid, raises the lowest IRR to 10.3%, with a range up to 17.9%.
In both cases, the BESS adds revenue streams that do not move in line with wind prices. At the optimum, the BESS earns 20%–46% of project revenue in the Green case and 38%–66% in the Grey case, for 12%–25% and 25%–47% of total CapEx. The best-performing Green system is a 2-hour BESS in every scenario, while 4- to 8-hour systems lead in most Grey scenarios.
The five things to know
01A BESS adds revenue streams. Charging from the grid adds more.
Wind alone sells into one price curve. A Green BESS adds three streams: day-ahead arbitrage, intraday trading and positive aFRR capacity, together 20%–46% of project revenue. A Grey BESS uses the same markets without waiting for surplus wind, and it can also sell negative aFRR capacity. Its share rises to 38%–66%.
02Wind alone barely clears the cost of capital. Both BESS variants fix that.
Standalone wind earns 7.5%–12.5% IRR and lands within 100 bp of the 8% hurdle in three of five scenarios. With a Green BESS the range moves to 8.4%–14.1%, and every scenario clears the WACC. With a Grey BESS it moves to 10.3%–17.9%, about 2 to 4 pp above the Green result in each scenario.
03The Green BESS optimises the wind park. The Grey BESS trades.
A Green BESS earns 20%–46% of project revenue with 12%–25% of the CapEx. It stores wind energy when the wind park pushes prices down and sells it when prices recover. A Grey BESS earns 38%–66% of revenue with 25%–47% of the CapEx. It still takes up wind surplus, but it no longer depends on it and can charge whenever power from the grid is cheap.
04Size for value, not for maximum capacity. The right size depends on whether the BESS can charge from the grid.
The NPV-maximising Green BESS is a 2-hour system of 10–25 MW in all five scenarios. Longer durations add cost but little revenue, because the BESS can only charge when the wind park has surplus. The best-performing Grey BESS configuration is a 25 MW asset with 4 to 8 hours duration in most scenarios. By importing from the grid, the asset can earn revenues continuously, also when the wind park is not generating, and hence recover the cost of the additional storage hours.
05Zero curtailment is the wrong target.
Sizing a Green BESS to eliminate curtailment costs €16M–€29M of NPV compared with the optimum. The largest systems remove most of the curtailment, but the extra capacity costs more than the recovered energy is worth. For a Grey BESS the picture is different: because it also charges from the grid, its size has little effect on curtailment, which falls only 6%–41% even at the largest size (Green: 90%–98%). Chasing the lowest-curtailment size still costs €1.2M–€12.6M of NPV.
Wind Only · Green BESS · Grey BESS
5-scenario comparison
IRR Range
Risk Exposure
Share of scenarios within 100 bp of WACC
Revenue Diversification
Active revenue streams
Wind
Wind · BESS DA · Intraday · aFRR Cap+
Wind · BESS DA · Intraday · aFRR Cap ±
All three configurations use the same 55 €/MWh EEG floor. The difference between Green and Grey BESS comes only from the charging rule and the negative aFRR market it opens.
Methodology at a glance
Discount rate
8% WACC
Real · 2% CPI
Project horizon
30 years
2027–2056; BESS re-CapEx after 20 yr
BESS CapEx
≈150–225 €/kWh
total installed, duration-dependent
Sizing sweep
250 configs
25 sizes × 5 scenarios × 2 charging modes
NPV and IRR are 30-year project figures at 8% WACC, based on synthetic price data using weather-year 2024 benchmarks. Revenues are modelled in real terms; operating costs for the wind park and the BESS are conservatively escalated at 2% CPI p.a. All three configurations share the same 55 €/MWh EEG floor, so the Green versus Grey gap reflects the charging rule alone. Modelled scenarios are stress tests, not forecasts, and do not constitute investment advice. Full assumptions, interactive charts for both charging variants, and the complete methodology are available after registration below.
Model your own projects
Apply the methodology directly to your projects — with personalized scenarios, site parameters, and auditable results.